Yields on CCC junk bonds hit 18%, up from 12.5% in January (opens the source in a new tab)
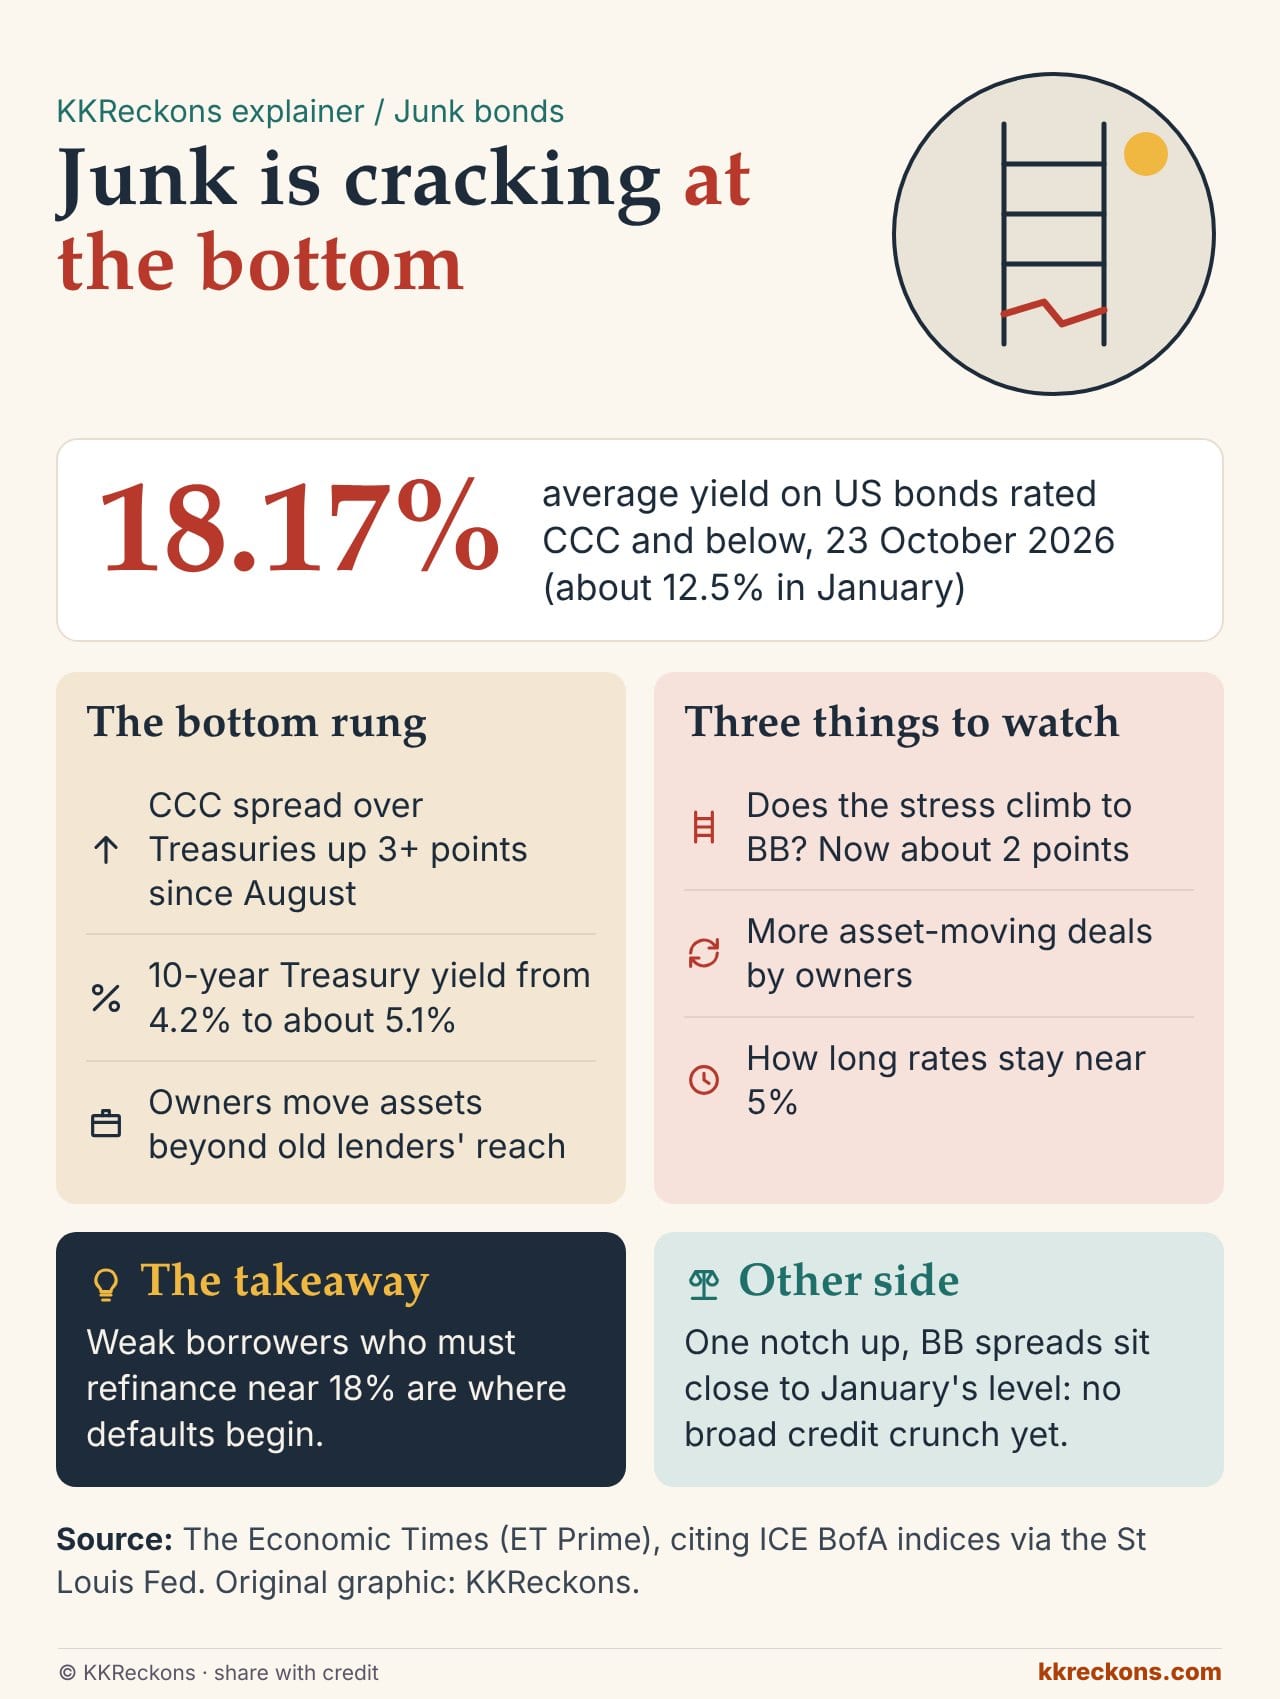
- ET Prime reports that the average yield on US bonds rated CCC and below, tracked by ICE BofA indices on the St Louis Fed's site, touched 18.17% on October 23, a three-year high and above the April 2025 tariff scare. It began 2026 near 12.5%.
- The pain sits on the bottom rung: BB-rated firms pay about two points over Treasuries, near January's level, while the 10-year Bond yield The annual return a bond pays at today's price; rising yields mean borrowing is getting dearer. rose from about 4.2% to 5.1%.
- It also flags owners moving prized assets, such as brands, into units beyond old lenders' reach, as J.Crew did in 2016-17, a question raised again at Aston Martin in July.
- 18.17%
- CCC-and-below yield, 23 Oct (≈12.5% in Jan)
- ~2 pts
- BB spread over Treasuries, near January
Why it matters Weak firms that must refinance at 18% are where defaults start, and asset-shuffling deals mean lenders may recover less when they do. The number to watch is the BB spread: if it widens, stress is spreading to sturdier borrowers and to the High-yield bond A bond from a riskier borrower that pays more interest to make up for the higher chance of default. and private-credit funds many investors hold.
Other side Trouble confined to the weakest credits is normal when rates rise. BB spreads near January's level suggest no broad credit crunch, and companies never stopped issuing junk bonds.