UPI's free ride ends for big merchant payments: who pays, who earns (opens the source in a new tab)
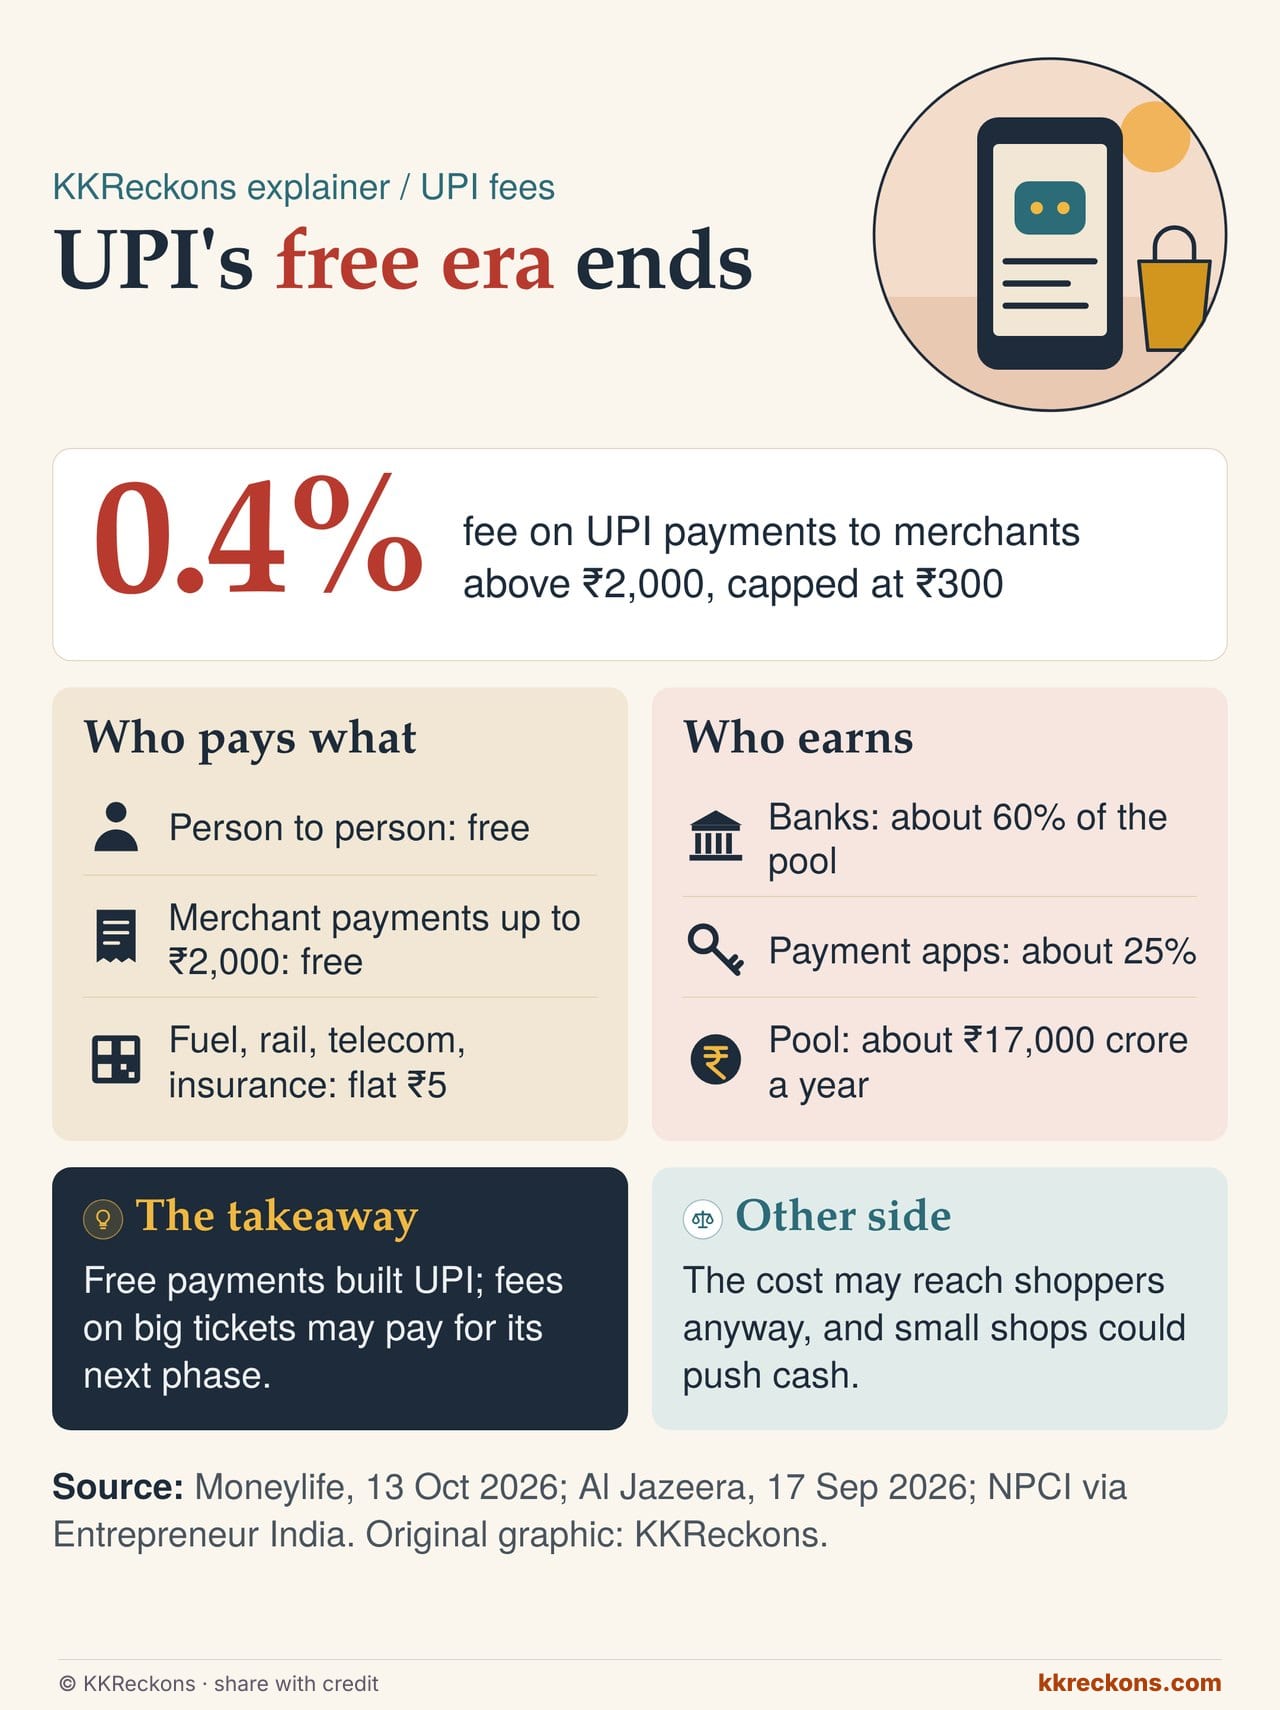
- NPCI's steering committee has set a 0.4% merchant fee on UPI Unified Payments Interface: India's instant mobile payment system, run by NPCI. payments to businesses above ₹2,000, capped at ₹300; fuel, rail, telecom and insurance pay a flat ₹5. Transfers between people stay free, and shops can't pass the fee on to customers.
- NPCI postponed the planned October 15 start, with a new date to be notified separately, Moneylife reported. NPCI says over 95% of merchant payments by volume are under ₹2,000.
- Al Jazeera says analysts see a pool of about ₹17,000 crore a year, roughly 60% to banks and 25% to apps; retailers warn small shops may rethink UPI.
- 0.4%
- fee on merchant payments over ₹2,000
Why it matters Zero fees made UPI everyone's default but left banks and apps carrying the cost with little direct return. A charge on bigger tickets gives them a revenue line for the first time, which could fund credit and other services built on the rails.
Other side Critics, including economist Santosh Mehrotra, say banks and apps already profited and the cost will reach consumers anyway. If shops see big-ticket UPI as costly, some may steer buyers to cash, eroding the adoption that made UPI work.
Also read: NPCI Announces 0.4% MDR on UPI Transactions Above INR 2,000