Chris Hughes: Recordati shows private equity’s self-dealing problem (opens the source in a new tab)
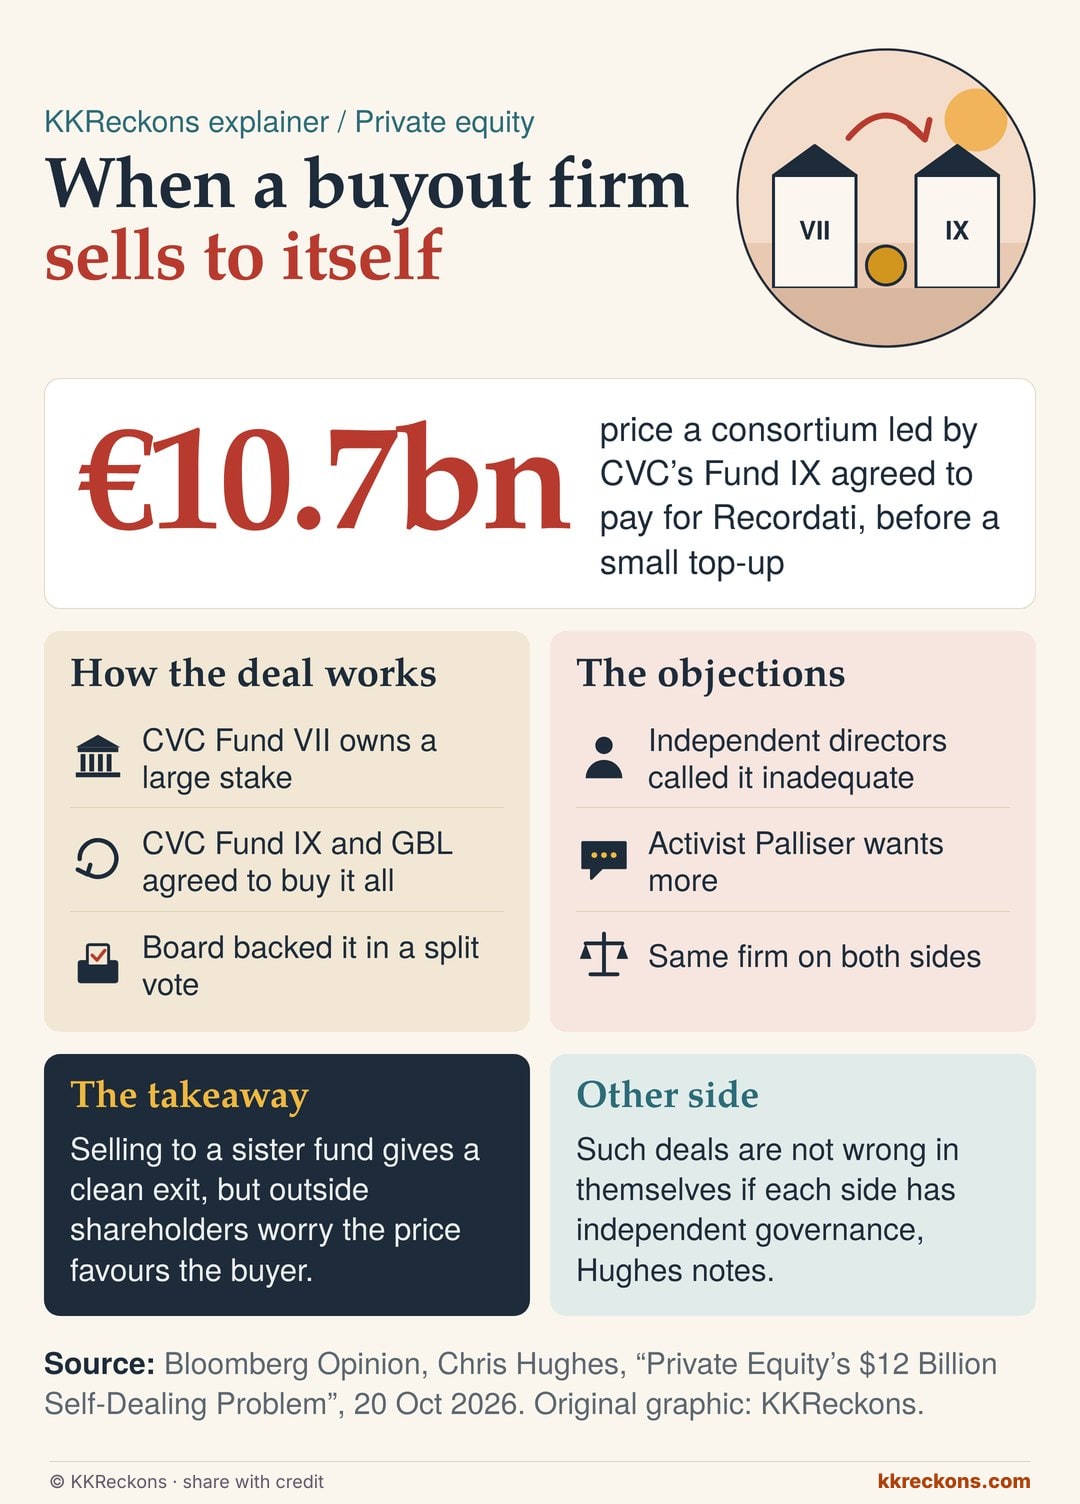
- CVC’s Fund VII has held 47% of Milan-listed drugmaker Recordati since a 2018 deal with the founding family, but a clean exit proved elusive.
- In May a consortium led by CVC’s Fund IX and Groupe Bruxelles Lambert agreed to buy the whole company for €10.7bn. The board backed it, but the independent directors called the price inadequate, and activist Palliser says a small top-up still is not fair.
- Columnist Chris Hughes argues the price looks skewed to the buyer; if the deal fails, Fund VII may have to sell its shares in the market at a discount.
- €10.7bn
- agreed price for Recordati
- 47%
- stake held by CVC Fund VII
Why it matters When one firm sits on both sides, minority shareholders carry the risk that the price serves the firm rather than them.
Other side Hughes himself notes such deals are not wrong in themselves if each side has independent governance, and the buyer brings fresh co-investors.