What makes a great investor: luck and an unusual temperament (opens the source in a new tab)
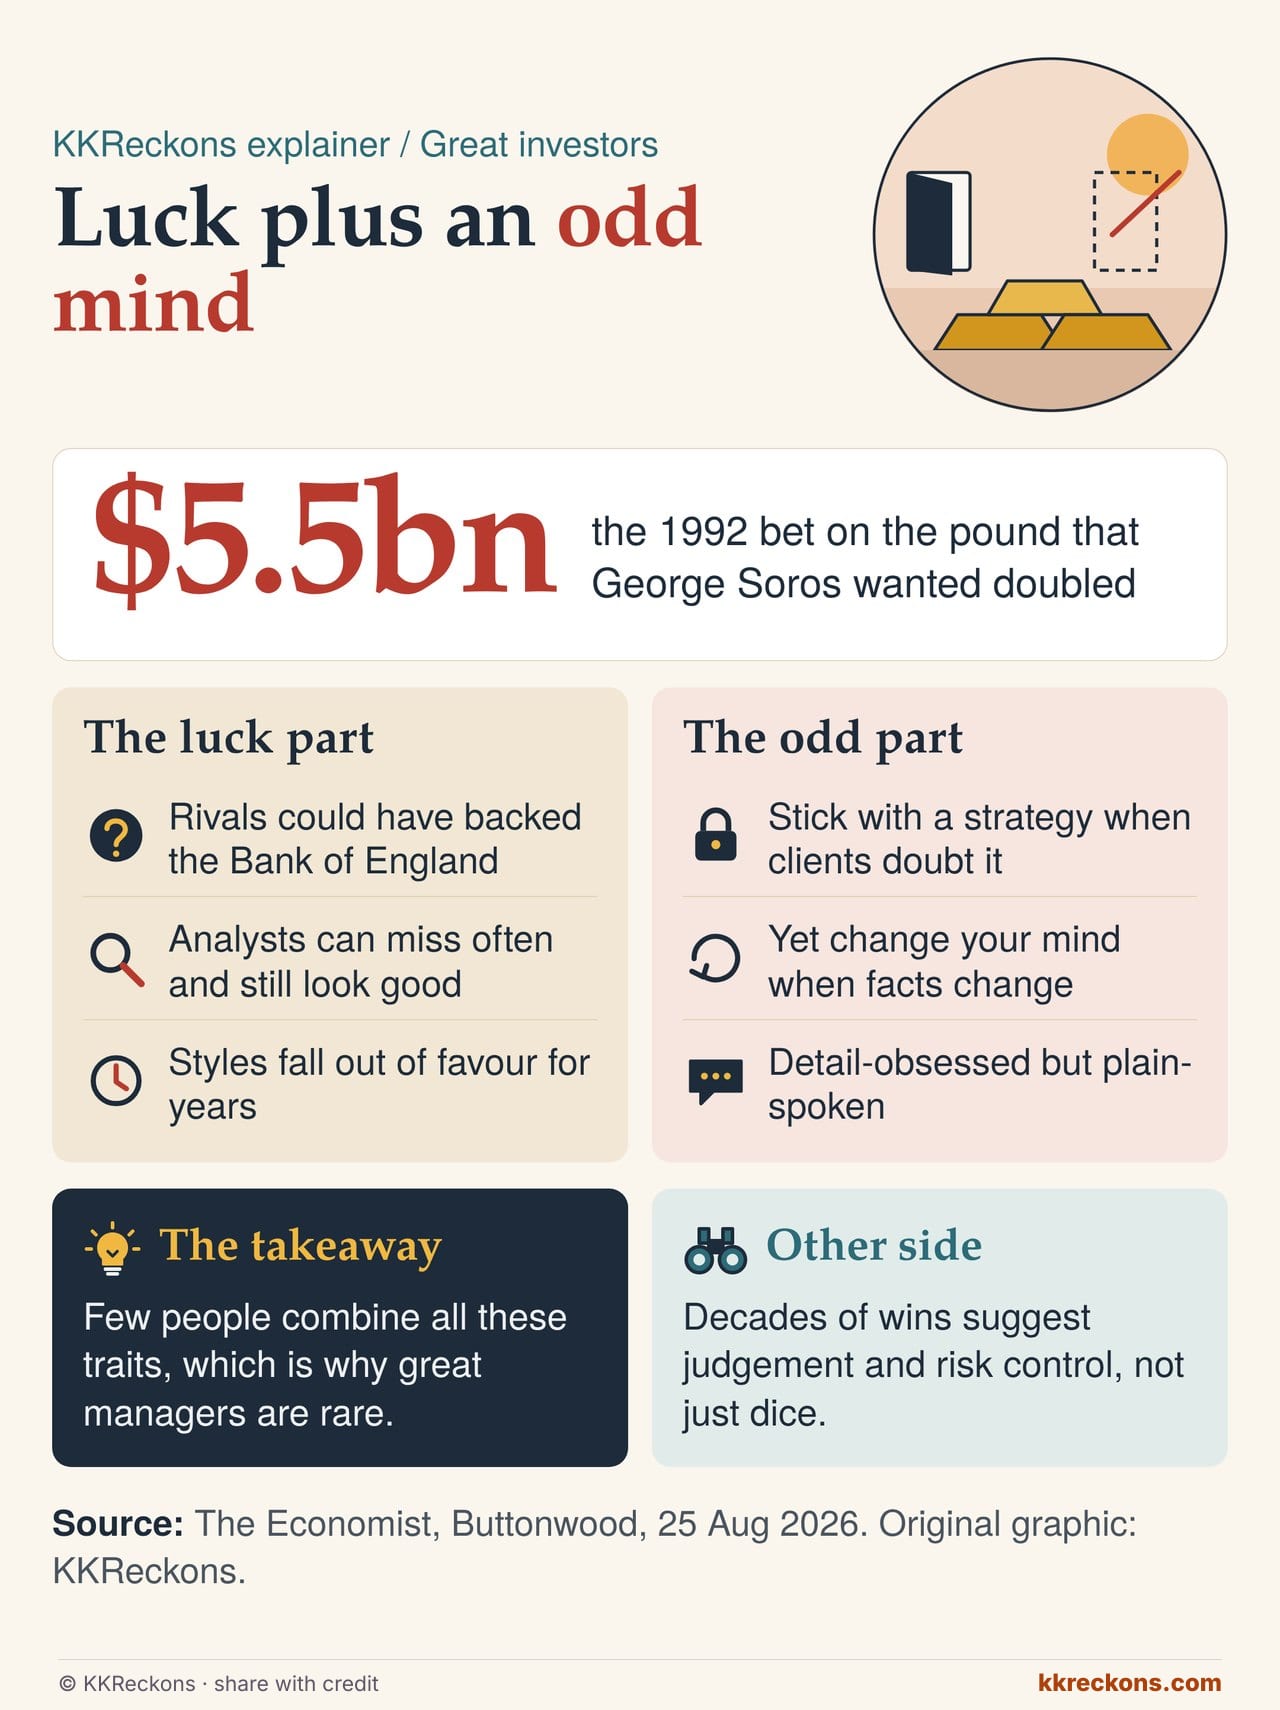
- The Economist's Buttonwood column revisits the 1992 bet against the pound, when George Soros told Stanley Druckenmiller to double a $5.5bn position, and argues luck mattered as much as nerve: other traders could have sided with the Bank of England.
- It notes analysts can be wrong often and still look excellent, and styles such as value investing fall out of favour for years; Cliff Asness stuck with his quant strategies until they worked again.
- Its verdict: greatness needs stubbornness plus the oddity to change your mind, a rare mix, so most savers may do better with an index fund.
- $5.5bn
- pound bet Soros wanted doubled, 1992
Why it matters Track records reward the survivors we hear about; telling skill from luck is the key question before paying any manager a premium fee.
Other side Calling winners lucky can be too easy: decades of success, like Soros's, point to judgement and risk control, not just dice.