CoreWeave shows the AI trade's weak spot: the borrowers (opens the source in a new tab)
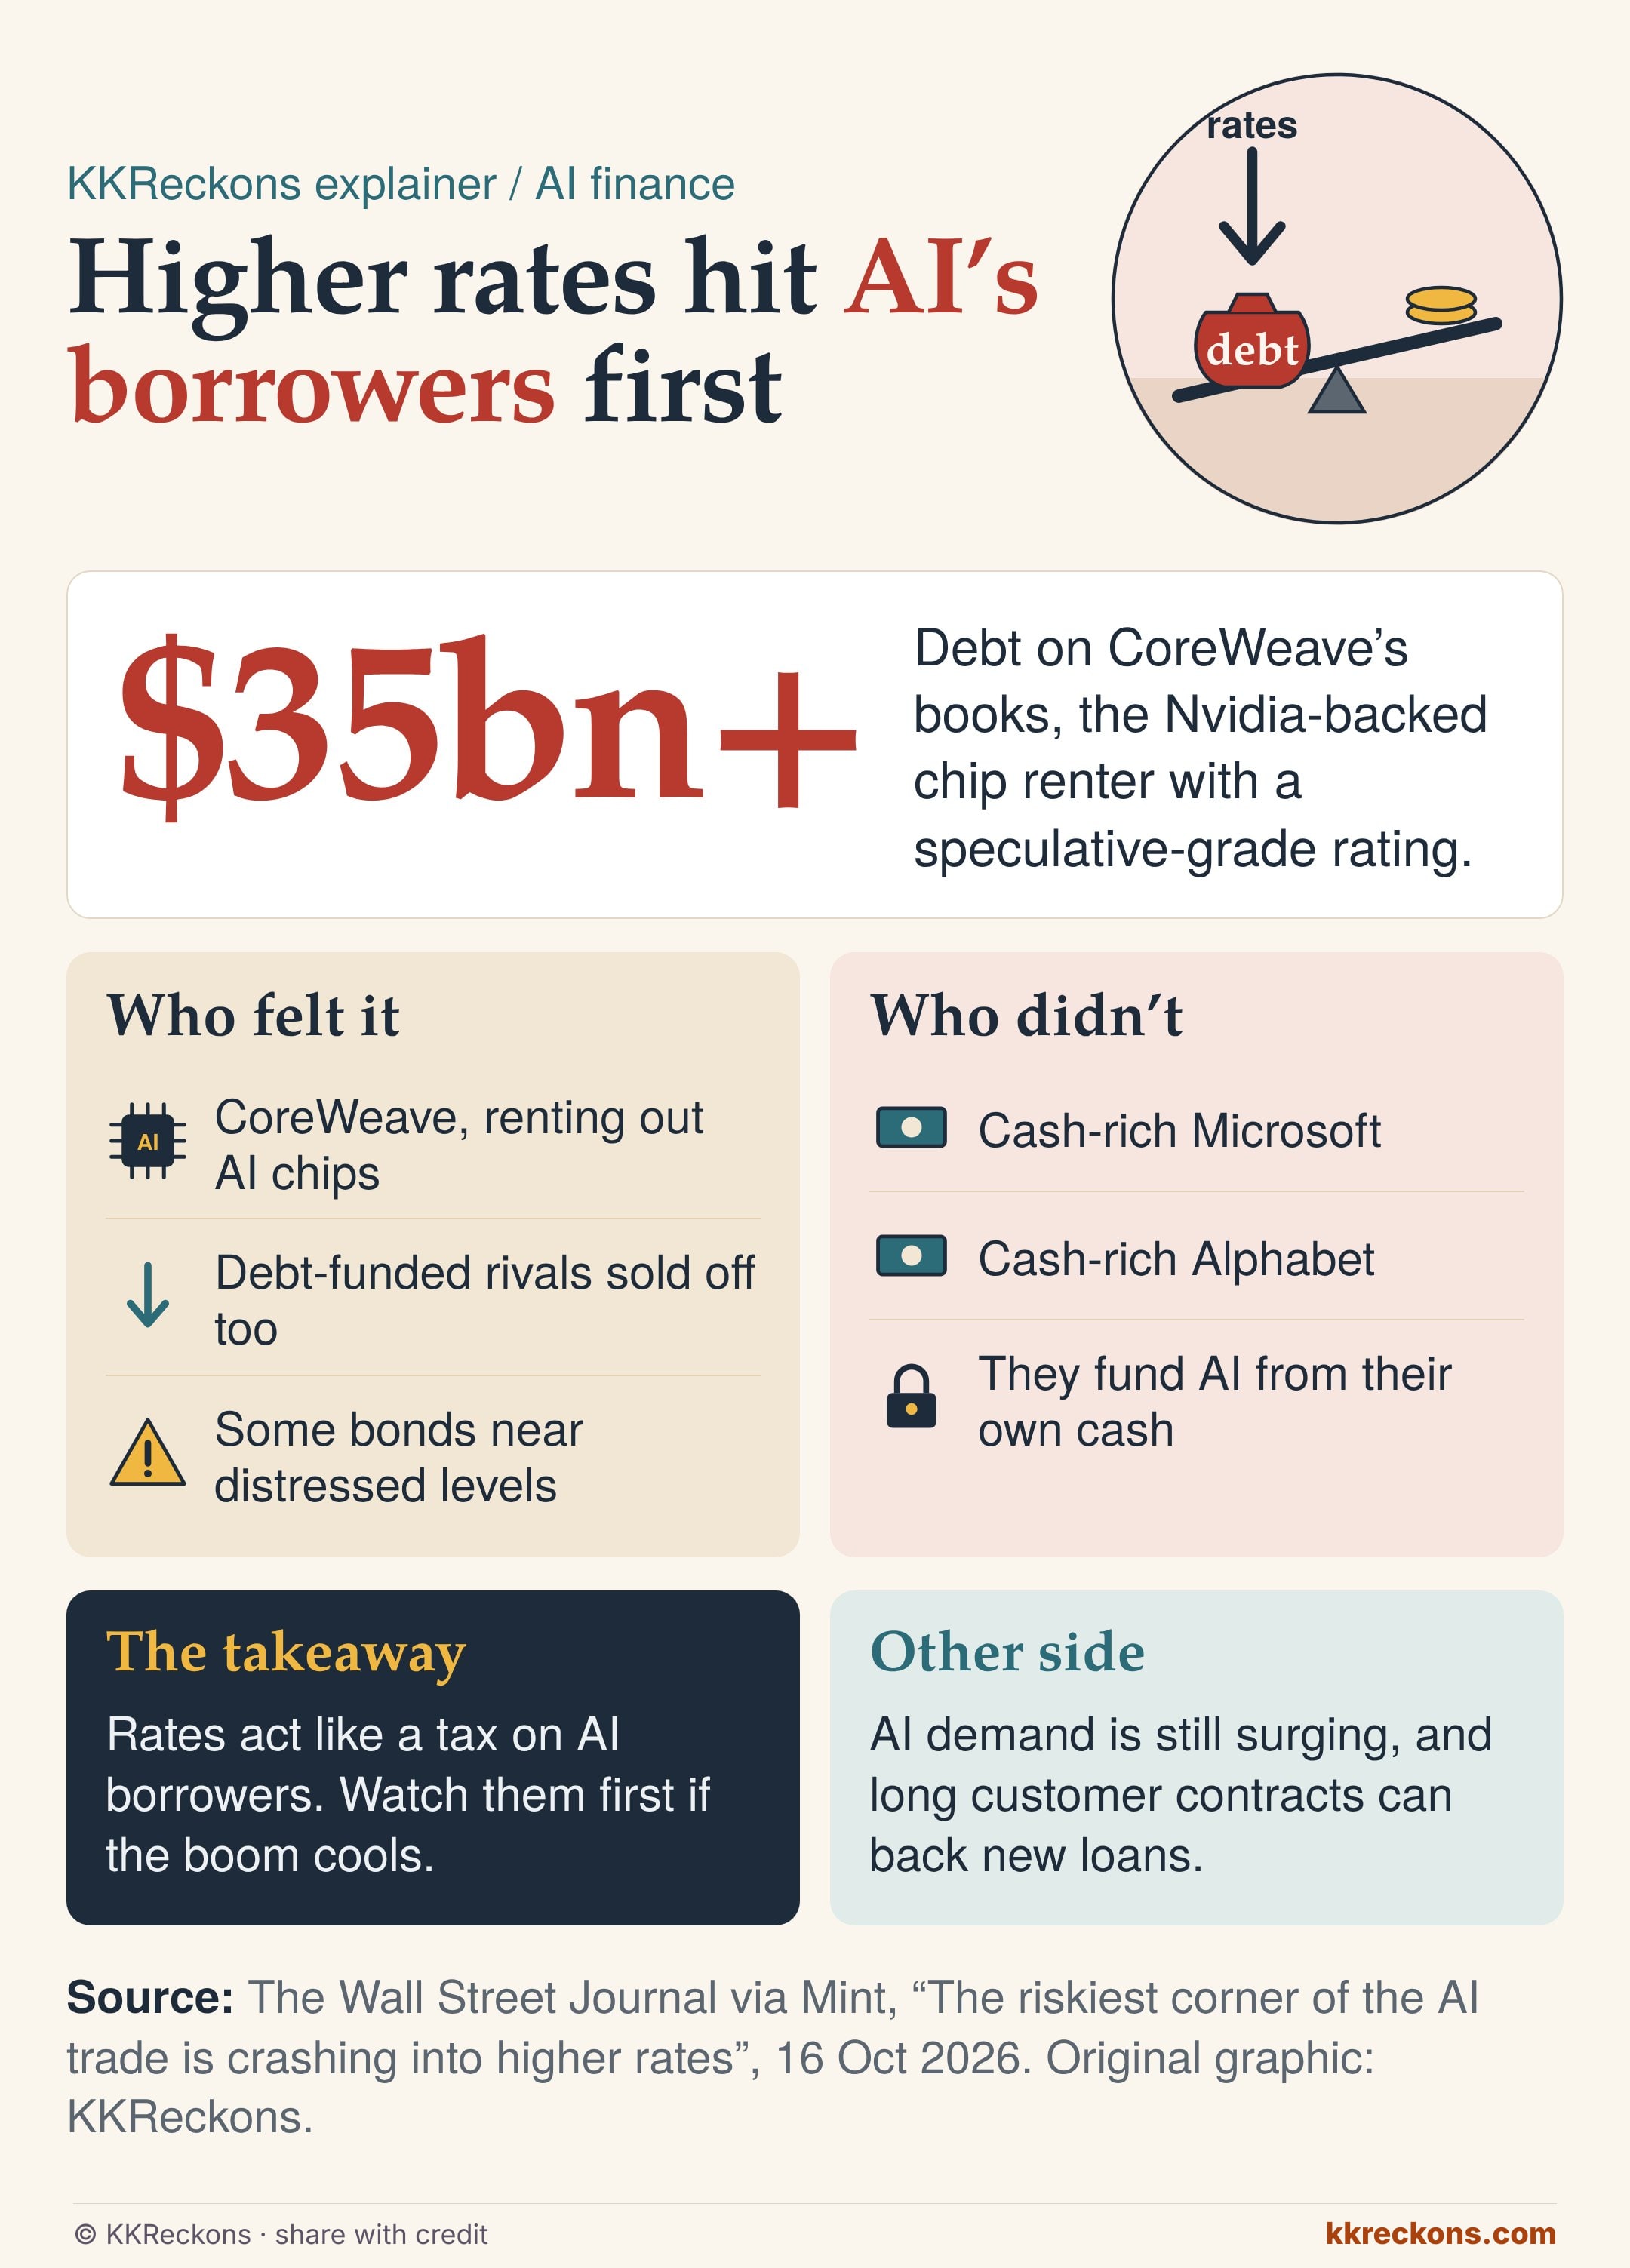
- Rising Bond yield The annual return a bond pays at today's price; rising yields mean borrowing is getting dearer. and fresh doubts about AI profits hit CoreWeave hard this week: its shares were down as much as 28% at one point, and some of its bonds traded at levels investors treat as distressed.
- The Nvidia-backed chip renter relies on borrowing to grow, carries at least $35 billion of debt and has a speculative-grade rating, unlike cash-rich Microsoft and Alphabet, which barely moved.
- Shares rebounded after Nvidia's Jensen Huang said CoreWeave was getting stronger. Analysts say it can still raise money through loans secured on customer contracts and through equity.
- $35bn+
- debt on CoreWeave's books
- 28%
- share fall at its worst
Why it matters Higher-for-longer rates act like a tax on anyone in AI who isn't a cash-rich giant. Watch the borrowers: they crack first if the boom cools.
Other side Demand for AI computing is still surging, Bank of America just raised its revenue forecasts, and long customer contracts can carry a borrower through a rough patch.